Canadian banks quarterly earnings. Canada’s largest financial institutions are approaching a closely watched earnings period, with investors preparing to examine whether the country’s banking sector can maintain its recent profit momentum amid changing interest rates, household debt pressures and uncertainty across the wider economy.
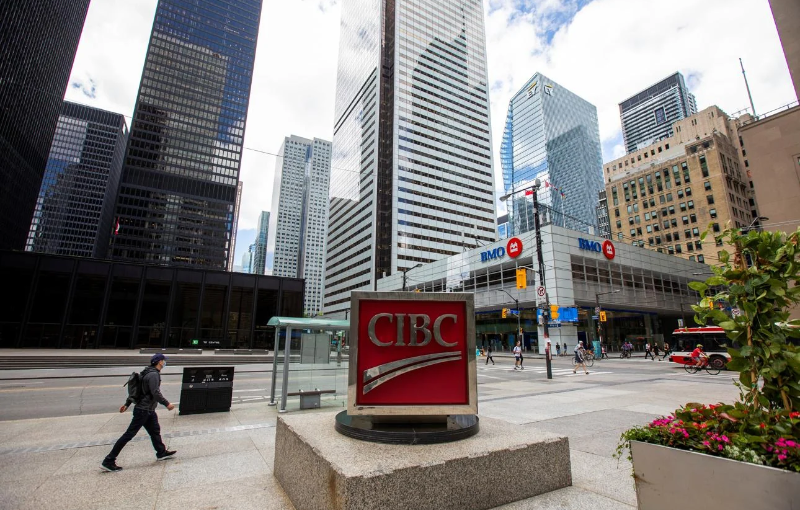
The upcoming Canadian banks quarterly earnings announcements will provide a fresh assessment of the financial performance of Royal Bank of Canada, Toronto-Dominion Bank, Bank of Montreal, Scotiabank, Canadian Imperial Bank of Commerce and National Bank of Canada.
The banks are scheduled to release their fourth-quarter and full-year fiscal 2026 results between December 2 and December 4. The announcements come after a strong third-quarter reporting season, when all six major lenders exceeded analysts’ profit expectations, supported by stronger capital-markets activity, wealth management and selected international banking operations.
However, investors are not expected to judge the next reporting season on profits alone. Credit-loss provisions, mortgage performance, lending growth, operating expenses and management guidance could determine how markets respond to the results.
For readers following the Canadian financial sector, Punjab Lens Media examines the issues likely to dominate the upcoming reporting period and the financial indicators investors should monitor.
Canada’s Big Six Banks Set December Reporting Dates
The upcoming reporting schedule will place Canada’s largest lenders under close market scrutiny over three consecutive days.
Bank of Montreal and Scotiabank are scheduled to release their fourth-quarter results on December 2. Royal Bank of Canada, TD Bank and CIBC are expected to publish their results on December 3, while National Bank of Canada has scheduled its announcement for December 4.
The reporting period will provide investors with a broader comparison of how individual institutions are managing interest-rate changes, lending conditions and economic uncertainty.
Royal Bank of Canada will be watched for performance across personal and commercial banking, wealth management and capital markets. TD’s results will offer insight into its Canadian and US operations, while BMO’s figures will help investors assess its commercial lending, capital markets and wealth-management businesses.
Scotiabank’s international operations and credit performance will remain important areas of attention. CIBC’s mortgage and personal banking exposure will also be closely examined, while National Bank’s results will provide another measure of the sector’s overall financial performance.
These announcements will form a major part of the upcoming Canadian banks quarterly earnings season.
Third-Quarter Results Provide a Strong Starting Point, but Risks Remain
The latest completed reporting season offered an encouraging picture of Canada’s banking industry.
During the third quarter of fiscal 2026, all six major Canadian banks beat analyst profit estimates. Reuters reported that stronger capital-markets activity was a significant contributor, with increased deal-making, trading revenue and investment banking activity supporting earnings.
Royal Bank of Canada’s capital-markets income increased 16% to C$1.54 billion, while its wealth-management profit rose 32%. CIBC recorded a 34% increase in capital-markets income, while TD reported an 87% increase in net income from its wholesale banking segment.
The results demonstrated the importance of diversified banking operations. Traditional lending remains central to the banks’ businesses, but wealth management, investment banking and financial-market activities can provide additional sources of revenue when borrowing conditions are less favourable.
Nevertheless, stronger quarterly profits do not automatically guarantee stronger share-price performance. Investors also consider whether earnings can be sustained, whether valuations already reflect positive expectations and whether credit risks are increasing.
The upcoming Canadian banks quarterly earnings announcements will therefore be judged against both recent performance and expectations for the next financial year.
Interest Rates and Net Interest Income Remain Central to Bank Profitability
One of the most important indicators investors will examine is net interest income, which measures the difference between the interest banks earn from loans and investments and the interest they pay on deposits and other funding.
Changes in interest rates can influence this figure in several ways. Lower borrowing costs may encourage households and businesses to seek financing, potentially supporting loan growth. However, falling lending rates can also reduce the amount banks earn from existing loans.
Deposit competition creates another challenge. Banks must balance the interest they offer savers against the revenue generated from their lending portfolios.
For this reason, investors should examine net interest margins alongside total net interest income. A bank could increase its overall interest income through stronger lending volumes even while its margin declines.
The Bank of Canada’s monetary policy will remain an important factor in the banking industry outlook. Its decisions influence mortgage rates, consumer borrowing costs, business financing and the broader economic environment.
For Punjab Lens Media, the relationship between interest rates and bank profitability is one of the central issues to watch during the next reporting season.
Rising Credit Risks Put Household Debt and Housing Markets Under Scrutiny
Credit quality is expected to remain another major focus as Canada’s largest lenders prepare their financial disclosures.
Canadian households continue to carry substantial debt, with mortgages, credit cards and personal loans representing important areas of exposure for financial institutions.
Mortgage renewals are particularly relevant because borrowers moving from older, lower-rate agreements to new financing arrangements may face different repayment obligations. The effect will vary according to household income, outstanding debt, property values and the interest rate attached to each renewal.
The housing market also matters because residential mortgages represent a significant part of Canadian bank lending.
Investors will examine mortgage arrears, impaired loans and changes in borrower repayment patterns to determine whether financial pressure is spreading across the lending market.
However, rising household debt should not automatically be interpreted as evidence of an impending banking crisis. The financial position of borrowers, underwriting standards, employment conditions and banks’ capital reserves all influence the actual level of risk.
The Canadian banks quarterly earnings reports should provide further information about how lenders are assessing these exposures.
Provisions for Credit Losses Could Influence Quarterly Profits
Provisions for credit losses, commonly referred to as PCL, are among the most closely watched figures in bank financial statements.
Banks set aside provisions to account for expected losses on loans and other credit exposures. When lenders anticipate that more borrowers could struggle to repay their debts, they may increase these provisions, reducing reported profitability.
A rise in provisions does not necessarily mean the same amount has already been lost. It reflects an estimate of potential future credit losses based on borrower conditions and economic assumptions.
Investors should examine whether provisions are increasing across residential mortgages, commercial lending, credit cards or other consumer credit portfolios.
The reasons behind the change are equally important. An increase associated with a specific commercial portfolio may carry different implications from a broader deterioration in household credit quality.
Management commentary on expected loan losses will therefore be an important part of the upcoming Canadian banks quarterly earnings announcements.
Capital Markets and Wealth Management Could Support Earnings Growth
Capital-markets operations and wealth management have become important contributors to the earnings of Canada’s major banks.
Investment banking revenue can increase when companies pursue mergers, acquisitions, financing transactions or public listings. Trading income may also benefit from higher market activity and volatility.
Wealth management provides another source of revenue through advisory services, investment products and fees linked to client assets.
The third-quarter 2026 results showed that these businesses helped support profitability across the sector. However, their performance can change considerably with financial-market conditions.
A strong quarter in capital markets does not necessarily mean that traditional lending operations are improving. Investors will need to distinguish between revenue generated by recurring customer activity and income influenced by temporary market conditions.
The next Canadian banks quarterly earnings reports will help establish whether recent growth across these divisions can continue into the new financial year.
How Could Earnings Results Affect Canadian Banking Stocks?
The relationship between bank earnings and share prices is more complicated than simply comparing reported profits with previous quarters.
Stronger-than-expected earnings can support investor confidence, particularly when banks also report stable credit quality, healthy capital levels and positive guidance.
However, a bank can exceed analyst estimates and still experience a decline in its share price. This can happen when investors had already expected stronger results, when valuations are high or when management provides a cautious outlook.
The reverse is also possible. A bank reporting weaker quarterly profits may receive a more favourable market response if investors believe the underlying business remains financially stable and future conditions are improving.
For investors tracking banking stocks in Canada, the most relevant questions include:
- Did the bank exceed or miss analyst expectations?
- Is adjusted earnings growth supported by its core banking operations?
- Are provisions for credit losses increasing?
- Is net interest income improving or declining?
- Has management changed its outlook for the coming year?
- Are dividend payments and capital-return plans sustainable?
These factors can influence how investors interpret the latest financial disclosures and reassess Canadian bank stock performance.
What Dividends and Management Guidance Could Tell Investors
Dividend announcements will remain important for shareholders who hold Canadian bank stocks for regular income.
Investors will examine whether banks maintain or increase dividend payments, how much capital they return through share buybacks and whether their financial positions support those decisions.
However, a higher dividend yield should not automatically be treated as evidence that a stock is attractively valued. Investors should consider earnings stability, capital adequacy, credit risks and future cash-generation capacity.
Management guidance will also receive significant attention.
Executives may discuss expectations for loan growth, interest margins, credit provisions, operating costs and the broader economic environment. Their comments can influence market expectations for the next financial year, particularly if they identify risks that were not fully reflected in previous forecasts.
For readers following Canadian banks quarterly earnings, these forward-looking statements may be just as important as the financial results themselves.
What the Results Could Reveal About Canada’s Wider Economy
The performance of major banks can provide useful information about the economic condition of Canadian households and businesses.
Loan demand can offer insight into consumer spending and business investment. Mortgage arrears and credit-card delinquencies can indicate whether borrowers are experiencing financial pressure. Commercial lending trends may also reveal whether companies are expanding, refinancing or delaying investment decisions.
A combination of weaker loan demand, rising credit provisions and deteriorating repayment conditions could signal increasing pressure across parts of the economy.
Conversely, stable credit quality, healthy lending activity and resilient bank profitability may suggest that financial institutions and their customers are managing economic uncertainty.
The Bank of Canada’s Financial Stability Report has identified household indebtedness and external economic uncertainty as important financial-system considerations. Investors should therefore examine bank disclosures alongside employment trends, housing-market conditions and monetary policy.
The Canadian banks quarterly earnings season will offer another opportunity to assess these wider economic signals.
How Investors Should Analyse Canadian Banks Quarterly Earnings
Financial results can contain a large amount of information, but several indicators deserve particular attention.
Net income and earnings per share: These figures show how much profit a bank generated and how much earnings are attributable to each share. Investors should compare reported and adjusted results with the same period last year.
Net interest income: This measure helps explain how effectively the bank generates revenue from lending and interest-bearing assets.
Provisions for credit losses: Investors should assess whether expected loan losses are rising, which portfolios are affected and what management expects in the coming quarters.
Loan and deposit growth: These figures help reveal customer borrowing demand, deposit competition and the bank’s ability to fund its lending activities.
Return on equity: This measure indicates how efficiently a bank generates profit using shareholders’ capital.
Capital adequacy: Common Equity Tier 1, or CET1, ratios provide insight into a bank’s ability to absorb financial losses and meet regulatory capital requirements.
Operating expenses: Technology investment, employee costs, regulatory compliance and other expenses can affect profitability even when revenue increases.
Dividend and management guidance: Investors should examine changes in dividend policies, share buybacks and management’s outlook for the next financial year.
A complete assessment should consider these indicators together rather than relying on a single earnings figure.
Punjab Lens Media will continue covering the financial developments, market trends and economic indicators that help readers understand Canada’s banking sector.
FAQ: Canadian banks quarterly earnings
Q1. When are Canadian banks quarterly earnings released?
Canadian banks publish financial results every three months. For the fourth quarter of fiscal 2026, BMO and Scotiabank are scheduled to report on December 2, RBC, TD and CIBC on December 3, and National Bank of Canada on December 4.
Q2. Which banks are included in Canada’s Big Six?
The Big Six consists of Royal Bank of Canada, Toronto-Dominion Bank, Bank of Montreal, Scotiabank, Canadian Imperial Bank of Commerce and National Bank of Canada.
Q3. Why do Canadian banks quarterly earnings matter to investors?
They provide information about bank profitability, lending activity, credit quality, capital strength and management expectations. These factors can influence banking-stock valuations and investor confidence.
Q4. What financial indicators should investors watch?
Investors should examine net income, adjusted earnings per share, net interest income, provisions for credit losses, loan growth, return on equity and capital adequacy.
Q5. How do interest rates affect Canadian banks?
Interest rates influence mortgage costs, lending demand, deposit expenses and net interest margins. The overall effect depends on each bank’s loan portfolio, funding structure and ability to adjust pricing.
Q6. Why are provisions for credit losses important?
They represent estimates of potential losses on loans and other credit exposures. Increasing provisions can reduce bank profits and may indicate that lenders expect greater repayment difficulties.
Q7. Do strong bank earnings always increase share prices?
No. Share prices also reflect investor expectations, stock valuations, future guidance, credit quality and wider market conditions. A bank can beat earnings estimates and still see its shares decline.
Q8. Where can readers follow Canadian banking news?
Readers can review official bank financial reports, investor presentations and management conference calls. Punjab Lens Media also covers Canadian business developments and financial-market news.
Conclusion: Canadian banks quarterly earnings
The December reporting season will provide an important assessment of Canada’s largest financial institutions as they close their 2026 fiscal year.
The previous quarter demonstrated that capital-markets activity, wealth management and diversified operations can support bank profitability. However, the sustainability of that performance will depend on lending conditions, credit quality, interest-rate movements and the wider economic environment.
Investors will need to look beyond headline profits and assess whether banks are generating sustainable earnings while maintaining sufficient capital to manage potential financial risks.
The upcoming Canadian banks quarterly earnings announcements will help determine how the country’s largest lenders are positioned for the next financial year.
For continued coverage of Canadian banks quarterly earnings, business developments, economic trends and financial markets, follow Punjab Lens Media at https://punjablensmedia.com/.